 Special Offer: Try the 'Elite Trading Circle Membership' for ONLY $37!
CLICK HERE TO LEARN MORE
Stocks are beginning the week near record highs as the current bull market celebrates its fourth anniversary. Yet beneath the market’s resilience, new challenges are emerging. Rising oil prices, elevated Treasury yields, concerns about the strength of the AI trade, and a pivotal week of inflation reports and corporate earnings are creating an increasingly complicated environment for investors.
The S&P 500 and Nasdaq finished last week with gains despite considerable volatility, demonstrating that buyers remain willing to step in during periods of uncertainty. However, Monday’s trading has been mixed, with energy and select technology stocks finding support while much of the broader market remains cautious ahead of several important catalysts.
I remain bullish on the longer-term market outlook, but I also believe the next phase of this rally will require stronger earnings, broader market participation, and some relief from inflationary pressures.
Energy prices have returned to the center of the market conversation following renewed attacks in Saudi Arabia and ongoing tensions involving Iran. Brent crude has climbed above $100 per barrel, raising concerns that higher fuel and transportation costs could keep inflation elevated.
At the same time, President Trump has announced progress toward a potential Russia-Ukraine agreement to halt attacks on energy infrastructure, alongside discussions involving Russian diesel supplies. These developments offer the possibility of some relief to global energy markets, although uncertainty surrounding the proposed arrangements remains significant.
The conflicting headlines illustrate why oil remains such an important market indicator. Further supply disruptions could push prices higher and pressure consumers and businesses, while diplomatic progress could provide relief.
Treasury yields are another important concern. The 10-year yield has recently traded above 5%, increasing borrowing costs and placing pressure on equity valuations. With the bond market closed Monday for the federal holiday, investors will be watching closely when Treasury trading resumes Tuesday.
If oil prices and bond yields continue moving higher together, the Federal Reserve could find itself facing an even more difficult inflation environment.
Artificial intelligence remains a powerful force behind the market’s advance, but recent trading has exposed some vulnerabilities.
The S&P 500’s gains have become increasingly concentrated in a relatively small group of technology and semiconductor companies. More than four in ten index constituents have declined this year, highlighting the gap between headline index performance and the experience of many individual stocks.
Recent concerns surrounding AI infrastructure spending, profitability, and growing semiconductor competition have also contributed to volatility in technology shares. Investors are increasingly looking for evidence that massive AI investments are producing sustainable earnings growth rather than simply supporting higher valuations.
This week’s semiconductor earnings, particularly from ASML and Taiwan Semiconductor, will offer an important test of that thesis.
I continue to favor the long-term opportunities surrounding AI, but believe selectivity will become increasingly important as investors distinguish companies with durable earnings potential from those benefiting primarily from speculation.
Third-quarter earnings season begins in earnest this week, with JPMorgan Chase, Goldman Sachs, Citigroup, and Wells Fargo among the major financial institutions preparing to report.
Bank results will provide valuable insight into consumer spending, borrowing conditions, credit quality, and the broader health of the economy. Higher interest rates can benefit certain banking operations, but they also create challenges for lending activity and borrowers.
Beyond the financial sector, investors will closely examine corporate guidance, profit margins, and management commentary about rising costs.
Strong earnings could help justify current valuations and extend the bull market. Disappointing guidance, particularly from companies heavily exposed to consumer spending or AI investment, could prompt another round of market volatility.
Monday, October 12: U.S. stock markets remain open, while the bond market is closed for Columbus Day. Oil prices, geopolitical developments, and positioning ahead of earnings remain the focus.
Tuesday, October 13: Major bank earnings begin, including JPMorgan Chase, Goldman Sachs, Citigroup, and Wells Fargo. The NFIB Small Business Optimism Index provides an additional economic update.
Wednesday, October 14: September Consumer Price Index (CPI), the week’s most important inflation report. The Federal Reserve’s Beige Book and additional bank earnings, including Bank of America and Morgan Stanley, will also be closely watched.
Thursday, October 15: Producer Price Index (PPI), retail sales, weekly jobless claims, and the Philadelphia Fed manufacturing survey. Taiwan Semiconductor’s earnings will provide a major update on AI and semiconductor demand.
Friday, October 16: Industrial production data, additional financial-sector earnings, and Federal Reserve commentary will help shape expectations heading into the following week.
The biggest potential market-moving combination will be Wednesday’s CPI report followed by Thursday’s inflation, consumer spending, and semiconductor updates. Together, these releases could significantly influence interest rate expectations and near-term market direction.
Despite these challenges, my broader market outlook remains unchanged. I continue to believe the longer-term uptrend is intact, supported by corporate earnings, technological innovation, and the resilience of the U.S. economy.
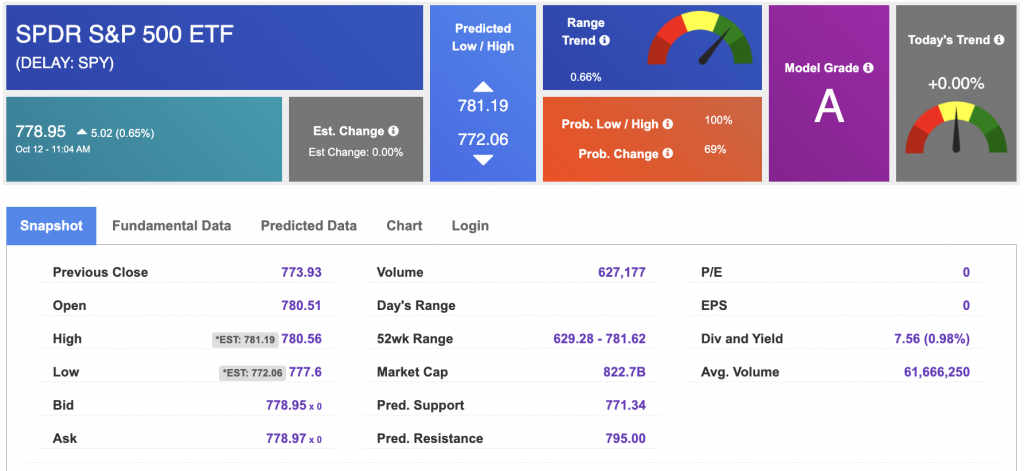
My upside target for the SPDR S&P 500 ETF (SPY) remains $760–$780, while I continue to monitor $700–$720 as an important support region.
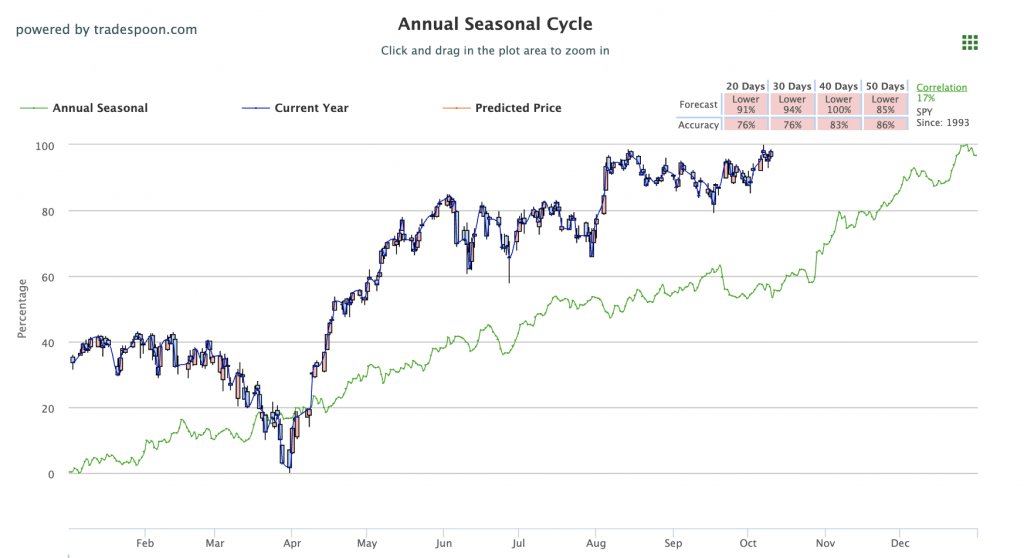
The VIX has recently traded in the mid-to-upper teens, indicating that investors have not yet moved into a sustained period of heightened fear. However, I will be watching volatility alongside SPY’s relationship with its 50-day moving average and the strength of broader market participation.
The most constructive scenario would involve moderating inflation, stabilizing Treasury yields, and strong earnings guidance that encourages investors to move beyond a handful of market leaders.
Conversely, another surge in oil prices or a hotter-than-expected inflation report could produce additional selling pressure, particularly in richly valued technology stocks.
For now, I continue to favor a disciplined approach that balances participation in the bull market with careful risk management and selective entry points.
The bottom line: The bull market has survived four years of economic uncertainty, but the next leg higher will need confirmation from earnings and inflation data. With several major reports arriving this week, investors should remain alert, flexible, and prepared to take advantage of opportunities created by volatility.
At Tradespoon, we will continue monitoring these developments and using our data-driven tools to identify promising trading opportunities as the market navigates this critical stretch.
Please share this Tradespoon Market Commentary with your friends.


Comments Off on
Tradespoon Tools make finding winning trades in minute as easy as 1-2-3.
Our simple 3 step approach has resulted in an average return of almost 20% per trade!