 Are you a Long-Term Trader? Then take a look at our NEW RoboInvestor Service?
CLICK HERE TO LEARN MORE
Monday Market Outlook | November 16, 2026
Wall Street faces a pivotal week as Nvidia’s leadership shakeup and upcoming earnings put the AI rally to the test. Persistent inflation, elevated Treasury yields, and a hawkish Federal Reserve are adding pressure, while major retail earnings and economic reports could determine the market’s next move. Despite the uncertainty, I remain bullish on the longer-term outlook, with several important technical levels in focus.
Wall Street enters the week of November 16 facing another round of volatility as investors weigh ongoing inflation concerns, elevated interest rates, geopolitical uncertainty, and renewed selling in artificial intelligence stocks. Technology shares have come under particular pressure following Nvidia’s unexpected leadership shakeup, raising questions about the sustainability of the AI-driven rally. Despite these near-term challenges, I remain in the MARKET BULLISH camp, although I expect market conditions to favor selective opportunities and disciplined risk management over aggressive broad-market exposure.
Nvidia (NVDA) has become the market’s biggest story. The sudden resignation of longtime CEO Jensen Huang last week sent shockwaves through the technology sector, with CFO Colette Kress stepping in as interim CEO. Shares have continued to face selling pressure, dragging semiconductor and AI-related companies lower. Investors are now turning their attention to Nvidia’s earnings report on Tuesday, November 17, after the market closes. Beyond revenue and earnings, the company’s outlook for AI infrastructure demand, data-center spending, and its leadership transition will be critical in determining whether confidence returns to the sector.
The broader AI investment theme remains intact, but investor expectations are changing. Strong results from CoreWeave (CRWV), including accelerating revenue growth and increased full-year guidance, reinforced the significant demand for AI infrastructure. However, rising capital expenditures, financing costs, and concerns about valuations are creating greater separation between companies delivering measurable financial results and those relying heavily on future growth expectations. The anticipated public offering of AI developer Anthropic later this week could further influence investor sentiment and capital flows across the sector. The market is shifting from buying AI growth at almost any price to demanding proof of profitability, sustainable demand, and financial discipline.
Inflation and Federal Reserve policy remain the other major obstacles. October’s Consumer Price Index rose 0.4%, while Friday’s Producer Price Index increased 0.3% for the month and a substantial 6.5% from a year earlier. Although the monthly wholesale inflation reading offered some relief, overall price pressures remain persistent. The benchmark 10-year Treasury yield was still above 5.1% early Monday, keeping pressure on equity valuations and borrowing costs. Federal Reserve Chair Kevin Warsh’s scheduled Monday remarks and Wednesday’s release of the October FOMC meeting minutes will receive significant attention as investors assess whether additional interest rate hikes may be necessary in December.
Corporate earnings and economic data will provide another important test of market resilience. Results from Home Depot, Disney, Target, Lowe’s, and Walmart will offer insight into consumer spending, retail demand, and the impact of higher borrowing costs. Tuesday’s retail sales and industrial production reports, Wednesday’s housing data, and Thursday’s initial jobless claims will help investors evaluate whether the economy can maintain its momentum. The challenge remains balancing economic strength against inflation that could keep monetary policy restrictive for longer than investors anticipated.
Geopolitical risks also remain in focus. Tensions involving Iran and shipping activity around the Strait of Hormuz continue to influence energy markets, while trade restrictions and semiconductor export policies present additional uncertainty for multinational technology companies. Although crude oil prices moved lower early Monday, the potential for renewed energy price increases remains an important inflation risk. These developments, alongside the aftermath of the midterm elections, could continue driving sector rotation and short-term market swings.
From a technical perspective, the broader market remains at an important crossroads. Stocks were trading near their 50-day moving average last week, while the VIX hovered around 18–19 before climbing above 20 early Monday. This rise in volatility reflects growing uncertainty, but it does not necessarily signal the end of the longer-term bullish trend. I will be monitoring semiconductor performance, Treasury yields, and market breadth for signs that buying pressure is returning. Stronger participation across sectors would help confirm a more sustainable recovery rather than another short-lived rally driven by a handful of large technology companies.
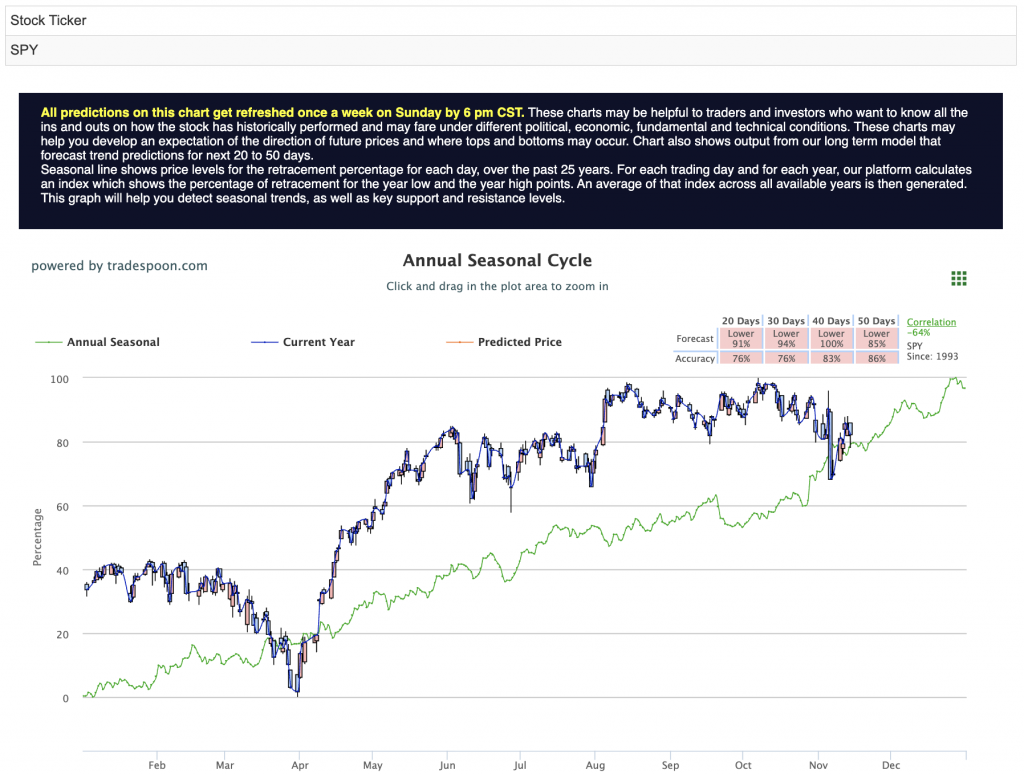
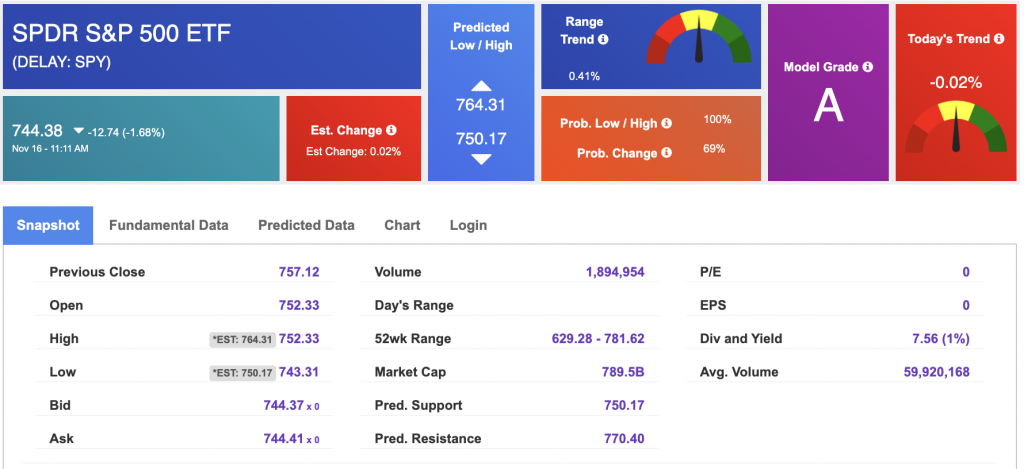
My outlook for the SPDR S&P 500 ETF Trust (SPY) remains constructive, with a potential rally toward $780–$810 over the next several months. Corporate earnings growth, continued AI investment, and underlying economic resilience remain important supports for the longer-term bullish case. However, elevated interest rates and continued technology-sector weakness could generate additional volatility along the way.
On the downside, I am monitoring $740–$750 as an important initial SPY support zone, with the broader $720–$740 area becoming increasingly significant should selling pressure intensify. A sustained rebound in technology stocks, improving market breadth, and greater stability in Treasury yields would strengthen the case for the next move higher.
Looking Ahead: Nvidia’s Tuesday earnings, Wednesday’s FOMC minutes, major retail results, and the anticipated Anthropic IPO make this a particularly consequential week for Wall Street. Strong earnings and reassuring economic signals could restore confidence and support renewed upside momentum. Disappointing guidance, persistent inflation, or additional weakness in semiconductors could instead extend the recent pullback.
The bottom line: I remain bullish on the market’s longer-term prospects, but the next stage of the rally will require more than enthusiasm for artificial intelligence. Earnings growth, corporate profitability, monetary policy, and broader market participation will ultimately determine whether stocks can sustain their upward momentum. Investors should remain selective, monitor key support levels, and be prepared to take advantage of opportunities as volatility creates attractive entry points.
Please share this Tradespoon Market Commentary with your friends.


Comments Off on
Tradespoon Tools make finding winning trades in minute as easy as 1-2-3.
Our simple 3 step approach has resulted in an average return of almost 20% per trade!